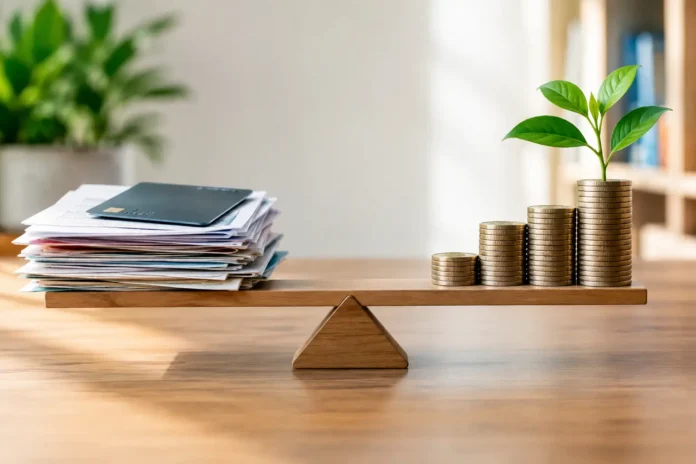
A credit card charging 24% interest and a diversified stock portfolio with a long-run expected return of 7% do not present a close call. Yet debt payoff versus investing becomes less obvious when the debt is a 3% mortgage, your employer offers a retirement match, or you have no emergency savings.
The right answer is rarely an all-or-nothing rule. It is a decision about guaranteed returns, market risk, cash flow, and the time available for your money to compound. A disciplined plan can often include both goals, but the order matters.
Debt Payoff Versus Investing Starts With the Interest Rate
Paying down debt produces a return equal to the interest rate you avoid. If you pay off a credit card with a 20% annual percentage rate, you effectively earn a guaranteed 20% return on the money used for repayment. That return is not taxed, and it does not fluctuate with the market.
Investing offers a different type of return. Stocks have historically delivered strong long-term results, but no annual return is guaranteed. A diversified portfolio may decline sharply during a bear market, including during the same period you need money for debt payments. That uncertainty is why comparing a debt rate with an expected investment return is not a simple math exercise.
High-interest debt usually deserves priority. Credit cards, payday loans, and many personal loans can carry rates high enough that investing while making only minimum payments becomes costly. Interest keeps accumulating, which reduces the amount of income available to save and invest later.
Lower-rate debt requires more judgment. A fixed-rate mortgage at 3%, for example, may not be urgent to prepay if you have a long investing horizon and are building retirement savings. The same is often true for certain federal student loans, depending on their rate, repayment protections, and your overall financial position.
Build the Foundation Before Taking More Market Risk
Before directing every extra dollar to debt or investments, protect your ability to handle an unexpected expense. Without cash reserves, a car repair, medical bill, or job loss can force you to borrow again just after paying debt down.
A starter emergency fund can be modest, but it should be accessible and separate from money invested for long-term goals. Many households work toward three to six months of essential expenses over time. Someone with variable income, dependents, or a single-income household may need a larger cushion.
This step can feel slow when markets are rising. Still, investing money that may be needed next month creates pressure to sell at the wrong time. Cash reserves allow your investment portfolio to remain invested through normal market volatility.
There is also a behavioral benefit. A clear cash buffer makes it easier to follow a debt repayment plan consistently instead of relying on new credit whenever an emergency appears.
Do Not Ignore an Employer Retirement Match
An employer match is one of the strongest reasons to invest while paying off debt. If your employer matches part of your 401(k) contributions, contributing enough to receive the full match may provide an immediate return that is difficult to beat.
For example, suppose an employer matches 50% of the first 6% of salary contributed. A worker earning $60,000 who contributes $3,600 could receive an additional $1,800. Investment performance still matters after that, but the employer contribution begins as a substantial gain.
There are exceptions. If you are facing delinquent bills, an eviction risk, a utility shutoff, or extremely high-cost debt, stabilizing your finances may come first. But for many workers, a practical sequence is to contribute enough for the full match, then focus aggressively on expensive debt.
Be aware of vesting rules as well. Some employer contributions become fully yours immediately, while others require you to remain employed for a specified period. The match remains valuable, but understanding the plan rules helps you make an informed decision.
Compare Debt by Type, Not by Emotion
Not all debt creates the same financial risk. A mortgage used to purchase a home, a fixed-rate auto loan, and revolving credit card balances should not automatically receive the same treatment. Focus on interest rate, repayment terms, tax treatment where applicable, and the consequences of falling behind.
Credit card debt is particularly damaging because high rates and revolving balances can keep borrowers trapped for years. Paying more than the minimum is critical. The debt avalanche method, which directs extra payments to the highest-interest balance first, generally minimizes total interest costs.
The debt snowball method directs extra payments toward the smallest balance first. It may cost more in interest than the avalanche method, but it can create early momentum. If quick wins help you stick with the plan, the behavioral advantage can be worthwhile.
For lower-interest fixed debt, prepayment is a choice rather than an emergency. Some people value the certainty of being debt-free earlier, even if investing might produce a higher return over decades. Others prefer to invest consistently while making scheduled loan payments. Both choices can be reasonable when they fit a sustainable plan.
A Practical Order of Operations
A useful framework is to handle your money in layers rather than forcing a single answer to every debt payoff versus investing decision.
First, cover minimum payments on every debt. Missing payments can lead to fees, credit damage, and higher borrowing costs. Next, establish a starter emergency reserve so small surprises do not go onto a credit card.
Then contribute enough to capture any valuable employer retirement match, unless a financial crisis requires immediate attention elsewhere. After that, direct most available cash toward high-interest debt. Once those balances are eliminated, increase retirement contributions and invest toward other long-term goals while continuing normal payments on lower-rate loans.
This approach is not a rigid formula. A person with a 7% personal loan may reasonably prioritize repayment more heavily than a person with a 3% mortgage. Someone nearing retirement may favor debt reduction because they have less time to recover from market losses. A young investor with stable income and low fixed-rate student loans may reasonably invest more.
Consider Taxes, Time Horizon, and Liquidity
Taxes can change the comparison. Traditional 401(k) contributions can reduce current taxable income, while Roth contributions may provide tax-free qualified withdrawals in retirement. Taxable investment accounts offer greater flexibility, but selling investments can create capital gains taxes.
Time horizon matters just as much. Money needed within a few years should generally not be placed heavily in stocks simply because historical average returns appear attractive. Stock investing works best when you can tolerate temporary declines and leave the money invested for a long period.
Liquidity matters, too. Extra payments toward a mortgage or student loan are usually difficult to retrieve. Money in a savings account is available for emergencies, while money in a retirement account may face taxes and penalties if withdrawn early. Avoid becoming so focused on being debt-free that you leave yourself with no accessible cash.
Avoid the False Choice
The biggest mistake is treating investing and debt repayment as competing identities. You do not need to be either the person who pays off every loan immediately or the person who invests every spare dollar. Financial progress usually comes from a repeatable system: spend less than you earn, avoid high-cost debt, maintain cash reserves, invest consistently, and adjust when your circumstances change.
Review your plan after major changes in income, interest rates, family responsibilities, or employment benefits. A strategy that was sensible last year may need refinement after a raise, a new loan, or a market downturn.
The best next step is the one that improves your financial stability without sacrificing your long-term future. Pay down debt that is expensive or stressful, claim benefits such as an employer match when available, and keep building the habit of investing with patience and purpose.