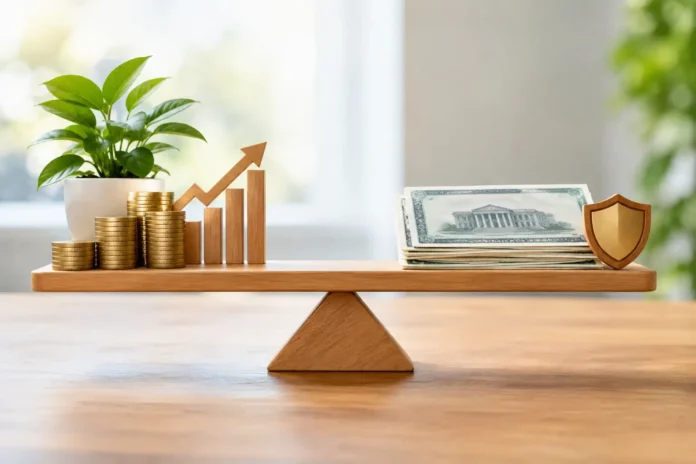
A portfolio can look diversified on paper and still be poorly matched to the investor who owns it. The central question in stocks versus bonds allocation is not which asset class will win next year. It is how much uncertainty you can accept in exchange for potential long-term growth, and how much stability you need along the way.
For many investors, the right answer changes over time. A 28-year-old saving steadily for retirement has different needs from a 60-year-old planning to use portfolio withdrawals within a few years. Your allocation should reflect that difference rather than a headline, a market forecast, or a popular rule of thumb.
What Stocks and Bonds Each Do in a Portfolio
Stocks represent ownership in companies. Their prices can rise substantially over long periods as businesses grow, generate profits, and pay dividends. They also fluctuate sharply. A broad stock market decline can reduce portfolio values by 20%, 30%, or more, sometimes over a relatively short period.
Bonds are loans made to governments, municipalities, or companies. In exchange, the issuer generally promises interest payments and the return of principal at maturity. High-quality bonds usually move less dramatically than stocks, although they are not risk-free. Rising interest rates can push bond prices down, inflation can reduce the purchasing power of fixed payments, and lower-quality issuers can default.
The value of combining them is not that one always rises when the other falls. Markets do not follow that rule consistently. Instead, stocks and high-quality bonds have often responded differently to economic conditions, which can reduce the severity of a portfolio’s swings. Bonds can also provide liquidity for near-term spending, allowing an investor to avoid selling stocks after a major decline.
Stocks Versus Bonds Allocation Starts With Time
Time horizon is usually the most practical starting point. Money needed soon should not depend heavily on a favorable stock market. If you expect to use funds for a home purchase, tuition payment, or retirement withdrawal within a few years, a large stock allocation could create an uncomfortable problem: the market may decline just when the money is needed.
Money with a long horizon has more time to recover from market setbacks. That does not make stocks safe in the short term, but it can make their volatility more manageable when you are saving consistently and do not need to sell. For retirement that is decades away, an investor may reasonably place more emphasis on growth than on current income or stability.
There is a useful distinction here. Your retirement date is not necessarily the end of your time horizon. A person retiring at 65 may need portfolio income for another 20 or 30 years. Moving entirely out of stocks at retirement can create a different risk: running short of purchasing power as inflation raises living costs.
Risk Capacity and Risk Tolerance Are Different
Investors often say they are comfortable with risk when markets are rising. A better test is how they would react after a steep decline. If a 30% drop would cause you to sell your investments and move to cash, your stock allocation may be too aggressive, even if you have a long timeline.
This is your risk tolerance – your emotional and behavioral ability to live with volatility. Risk capacity is more objective. It reflects whether a loss would threaten your financial plan. Someone with stable income, a substantial emergency fund, modest debt, and decades before needing portfolio money may have greater risk capacity than someone nearing retirement with limited savings.
Both matter. A mathematically appropriate portfolio is not useful if you cannot stick with it. Conversely, an overly conservative portfolio can also create problems if it does not provide enough expected growth to support future goals. The aim is not to eliminate risk. It is to choose risks you can understand and maintain through difficult periods.
Common Allocation Approaches
There is no universal stocks-to-bonds percentage, but a few broad patterns can help frame the decision. A growth-oriented investor with a long horizon might hold a larger share in diversified stock funds and a smaller allocation to bonds. A balanced investor might divide assets more evenly. An investor approaching a spending goal may hold a larger share in bonds and cash-like investments to reduce the chance of being forced to sell stocks at a loss.
You may see rules based on age, such as holding a bond percentage equal to your age or using 120 minus your age for stocks. These can be useful as rough starting points, but they are not financial plans. They ignore retirement income sources, health care needs, debt, job stability, pension benefits, and the size of your emergency savings.
Consider two investors who are both 45. One has a secure job, low expenses, no high-interest debt, and 20 years before retirement. The other expects to use part of the portfolio for a child’s college costs in five years. Their age is the same, but their appropriate allocations may not be.
Do Not Treat All Bonds as the Same
A bond allocation should be built with the job of the bonds in mind. If the purpose is stability, high-quality government bonds and investment-grade bonds may fit better than lower-quality, high-yield bonds. High-yield bonds can offer more income, but their prices may fall at the same time as stocks when economic conditions deteriorate.
Duration also matters. Bonds with longer maturities are generally more sensitive to interest-rate changes. Shorter-term bonds tend to fluctuate less when rates move, although they may offer lower yields. An investor using bonds for a near-term spending need may prefer less interest-rate sensitivity than an investor with a longer horizon.
Bond funds add another consideration. Unlike an individual bond held to maturity, a bond fund does not have one fixed maturity date. Its value will move as rates and credit conditions change. That does not make bond funds inappropriate. It means investors should understand what they own rather than assuming every bond investment behaves like a savings account.
Build the Allocation Around Your Full Financial Picture
Your investment account is only one part of your financial life. Before increasing stock exposure, make sure you have addressed immediate financial vulnerabilities. An emergency fund, manageable high-interest debt, and appropriate insurance can give you more ability to remain invested when life becomes expensive or uncertain.
Also consider investments outside the account you are reviewing. If your workplace retirement plan is heavily invested in stocks, your taxable account may not need to be equally aggressive. If you own a stable pension or expect guaranteed income that covers basic expenses, you may have greater flexibility with the remaining portfolio. The reverse can also be true.
Taxes matter as well. Interest from many taxable bonds is generally taxed as ordinary income, while stock investments may generate qualified dividends and long-term capital gains that can receive different tax treatment. Asset location – deciding which investments belong in taxable versus tax-advantaged accounts – is separate from allocation, but the two decisions often work together.
Rebalance With Discipline, Not Predictions
A target allocation will drift as markets move. If stocks rise strongly, they can become a larger percentage of your portfolio than intended. If stocks fall, the bond percentage can become larger. Rebalancing means returning the portfolio to its target mix by directing new contributions, selling part of an overweight holding, or buying what has become underweight.
This process can feel counterintuitive because it asks you to add to areas that have recently lagged and trim areas that have recently performed well. That is precisely why it can support discipline. Rebalancing is not a forecast that one asset class is about to outperform. It is a risk-management practice that keeps your portfolio aligned with the plan you chose.
Many investors review allocations once or twice a year, or when the mix moves beyond a predetermined range. Frequent adjustments based on daily market news usually create more activity than value. Keep trading costs, taxes, and account rules in mind before making changes.
Avoid the Most Common Allocation Mistakes
The most damaging error is often changing course after a market decline. Selling stocks after they have fallen can turn a temporary loss into a permanent one and leave you underinvested if the market recovers. A close second is owning more stock risk than you can tolerate because recent returns made an aggressive allocation seem easy.
Another mistake is treating bonds as unnecessary during strong stock markets. Stocks may outperform for extended periods, but bonds can become especially valuable when the portfolio needs stability, income, or a source of funds during a downturn. Finally, do not confuse complexity with diversification. A simple mix of low-cost, broadly diversified stock and bond funds can be easier to understand and maintain than a collection of overlapping investments.
Your allocation is not a prediction about the next recession, rate decision, or market rally. It is a personal operating plan for uncertain markets. Choose a mix that supports your goals, review it when your life changes, and make sure it is one you can hold when the headlines are at their worst.