A market crash rarely begins with a single dramatic headline. More often, it starts when investors become less willing to take risk at the same time that prices are already vulnerable. Understanding why markets crash can help you separate a painful but normal decline from a period when fear, forced selling, and uncertainty are feeding on one another.
For long-term investors, the goal is not to predict the exact date of the next crash. That is not realistic. The goal is to understand the forces involved, build a portfolio that can withstand stress, and make decisions from a plan rather than from panic.
What Makes a Market Decline a Crash?
Stock prices move down regularly. A pullback may last days or weeks, while a correction is commonly described as a decline of 10% or more from a recent high. A bear market is often defined as a decline of 20% or more.
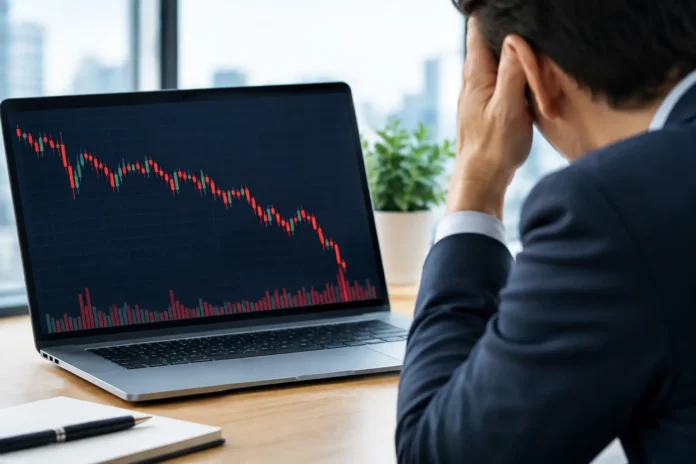
A crash is less about one precise percentage and more about speed and disorder. Prices fall sharply, volatility jumps, and investors rush to reduce risk. Trading can become heavily one-sided, especially in areas of the market that had attracted the most optimism beforehand.
The distinction matters because not every decline signals a broken economy or a permanent loss for a diversified investor. Markets routinely reassess prices. A crash is more likely when that reassessment becomes a self-reinforcing cycle.
Why Markets Crash: The Main Forces at Work
Markets are forward-looking. Investors do not buy stocks based only on what companies earned last quarter. They buy based on what they expect companies to earn in the future, how much risk they are willing to accept, and what return they can earn elsewhere.
When those expectations change quickly, prices can change quickly too.
A shock changes the economic outlook
A recession risk, banking stress, a geopolitical conflict, a pandemic, a major policy shift, or an unexpected rise in interest rates can all force investors to rethink future corporate profits. If consumers may spend less, businesses may earn less. If borrowing costs rise, expansion becomes more expensive and future cash flows are worth less in today’s dollars.
The initial shock does not need to be catastrophic. It only needs to be large enough to challenge the assumptions built into stock prices. When valuations are high and expectations are optimistic, disappointing news has more power to move markets.
High valuations leave less room for disappointment
A stock market can become expensive when investors expect strong growth, low inflation, easy financing, or continued enthusiasm for a popular sector. Those expectations may be reasonable, but they leave less margin for error.
Consider a company priced for years of rapid earnings growth. If growth merely slows, its stock can fall substantially even if the company remains profitable. Across the market, the same process can cause a broad decline: investors are not necessarily reacting to a collapse in current results, but to a lower estimate of what the future is worth.
Leverage turns selling into forced selling
Leverage means using borrowed money to invest. It can increase gains when prices rise, but it also magnifies losses when prices fall. Investors using margin may face a margin call, requiring them to deposit cash or sell holdings. Funds and institutions can face similar pressure through derivatives, debt, or other financing arrangements.
This is one reason declines can accelerate. A leveraged investor may not sell because they believe the investment is permanently damaged. They may sell because they have no choice. That forced sale puts more shares on the market, lowering prices and potentially creating pressure on other leveraged investors.
Liquidity can disappear when it is needed most
Liquidity is the ability to buy or sell an investment without causing a large price change. In normal conditions, there are usually many willing buyers and sellers. During a panic, buyers may step back, waiting for lower prices or clearer information.
With fewer buyers available, sellers may have to accept lower prices to exit. This is particularly relevant for thinly traded stocks, complex funds, and assets that are difficult to value. Even large, widely held stocks can experience unusually sharp swings when uncertainty is high.
Investor behavior creates feedback loops
Markets are made of people and institutions, each responding to prices, news, and one another. When investors see a falling market, they may assume someone else knows something they do not. That fear can encourage selling even before the facts are fully clear.
News coverage, social media, and market alerts can make the movement feel immediate and personal. A falling portfolio balance creates a strong emotional urge to stop the pain. Yet selling after a large decline can turn a temporary paper loss into a permanent loss.
This does not mean investors should ignore genuine risks. It means they should distinguish between a change in their investment thesis and the emotional discomfort of seeing prices fall.
How One Selloff Becomes a Broader Market Crash
Market crashes usually develop through a chain reaction. A negative event or weak economic signal causes prices to fall. Falling prices lead investors to reduce risk, which pushes prices down further. Leverage, fund redemptions, and low liquidity add pressure. As volatility rises, more participants act defensively.
Modern markets also include systematic strategies that respond to price trends or volatility. These strategies can reduce exposure when market conditions worsen. They are not inherently harmful, and they may follow sensible risk rules, but their collective actions can add to selling pressure in fast-moving markets.
At the same time, investors often sell what they can sell, not only what they want to sell. That is why high-quality companies can decline alongside weaker businesses during a broad panic. In the short term, the need for cash and the desire for safety can matter more than company fundamentals.
Eventually, prices may reach levels that attract long-term buyers. Policy responses can also help stabilize confidence, depending on the cause of the crisis. But timing that turning point is extremely difficult. Markets often recover before economic headlines feel reassuring.
What Crashes Mean for a Long-Term Investor
A crash is a test of preparation. Your best choices are usually made before markets are under pressure.
Start with an asset allocation you can live with through a major decline. If a 30% or 40% drop in stocks would cause you to abandon your plan, your portfolio may hold more stock risk than is appropriate for your goals, timeline, and temperament. Cash and high-quality bonds can reduce expected returns in strong markets, but they can also provide stability and spending flexibility during weak ones.
Diversification matters for the same reason. Owning investments across companies, sectors, and asset classes does not prevent losses in a broad crash. It reduces the risk that one company, industry, or country determines your financial outcome.
It also helps to match money to its purpose. Funds needed for a home purchase, tuition bill, emergency, or near-term spending should generally not depend on a stock market recovery. Money invested for a retirement decades away can usually tolerate more short-term volatility, provided the investor has a disciplined plan.
How to Respond When Markets Are Falling
When markets fall sharply, begin with questions rather than actions. Has your financial goal changed? Has your time horizon changed? Do you need this money soon? Has the reason you owned a particular investment materially changed?
If the answer is no, reacting to the market’s latest move may not improve your position. Review your allocation and rebalance only according to a pre-established approach. Rebalancing can mean selling a portion of what held up better and adding to what fell, but it should reflect your risk limits, taxes, and transaction costs.
Avoid treating a crash as automatic evidence that you should buy aggressively. Lower prices can create opportunity, but a purchase should still fit your plan. It depends on your emergency savings, debt, existing exposure, and ability to remain invested if prices continue downward.
Most importantly, do not confuse activity with control. Checking prices repeatedly may increase anxiety without improving decisions. A written investment policy, even a simple one, gives you a reference point when headlines are loud and confidence is scarce.
A market crash can feel like proof that investing is unsafe. In reality, it is proof that risk was always present. The disciplined investor does not eliminate that risk. They prepare for it, give their investments adequate time, and keep temporary market fear from making permanent decisions.