A stock can report strong earnings and still fall 10% in a day. Another company can have weak current profits and rise for months. Those outcomes are not contradictions. They show why investors need more than one way to interpret a market. The technical analysis vs fundamental analysis question is really about what you are trying to understand: the value of a business, the behavior of its shares, or both.
Neither method can remove uncertainty. Each provides a different set of evidence, works better in certain situations, and can lead to costly mistakes when used without discipline. Understanding the distinction helps you build a process instead of reacting to headlines, price moves, or confident opinions.
Technical Analysis vs Fundamental Analysis: The Core Difference
Fundamental analysis evaluates the underlying business. It asks whether a company earns money, has a durable competitive position, manages debt responsibly, and has a reasonable chance of growing over time. Its central question is: what is this business worth?
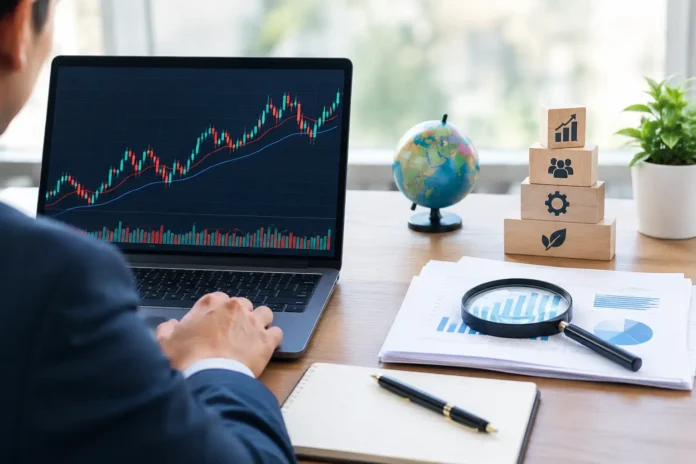
Technical analysis studies market data, primarily price and trading volume. It looks for trends, areas where buyers or sellers may become active, and patterns in market behavior. Its central question is: what are market participants doing now, and what might that suggest about the next price move?
Fundamental investors may review annual reports, earnings releases, profit margins, cash flow, debt levels, and industry conditions. Technical traders may use price charts, moving averages, support and resistance levels, volume, and momentum indicators.
The difference is not that one approach is serious and the other is speculative. Both require judgment. The real issue is time horizon and purpose. Fundamental analysis is usually more useful for deciding what to own over years. Technical analysis is often more useful for managing entries, exits, and risk over days, weeks, or months.
How Fundamental Analysis Works
A business is not the same thing as its stock price. In the short run, a share price can move because of interest-rate expectations, a disappointing forecast, broad market fear, or a crowded trade. Over longer periods, however, business results tend to matter a great deal.
Fundamental analysis begins with the company. An investor may ask whether revenue is growing, whether earnings are reliable, and whether the company produces free cash flow after paying its operating and investment costs. They may compare the business with competitors to see whether its margins, growth rate, or financial strength are genuinely better.
Valuation is the next step. A high-quality company is not automatically a good investment at any price. Common measures such as the price-to-earnings ratio, price-to-sales ratio, and price-to-free-cash-flow ratio can help investors compare a stock’s market price with its financial performance. These figures are useful starting points, not final answers. A fast-growing software company and a mature utility should not be valued by identical standards.
What fundamental analysis does well
Fundamental analysis helps investors avoid treating stocks as ticker symbols detached from real businesses. It encourages research into debt, management decisions, competitive threats, and the economic conditions that may affect future profits.
It is especially valuable when building a long-term portfolio. If you expect to hold a stock for five or ten years, the company’s ability to grow earnings and generate cash generally matters more than whether its chart is above or below a 50-day moving average this week.
Where fundamental analysis falls short
Fundamentals can tell you that a stock appears undervalued, but they cannot reliably tell you when the market will agree. A cheap stock can remain cheap for years. A business may also look attractive based on past financial statements while its industry changes quickly.
Investors can also become attached to their analysis. After spending hours researching a company, it is easy to dismiss warning signs because the original investment case feels persuasive. A written thesis, along with clear conditions that would prove it wrong, can reduce that risk.
How Technical Analysis Works
Technical analysis starts with the view that price and volume reflect the combined actions of buyers and sellers. A chart does not explain why investors are buying or selling. It shows the result of those decisions.
A technician may identify an uptrend by looking for higher highs and higher lows. They may watch a prior price area where a stock repeatedly found buyers, known as support, or an area where sellers repeatedly emerged, known as resistance. Rising volume during a breakout can suggest stronger participation, while declining volume may signal less conviction.
Moving averages are another common tool. They smooth daily price changes and can help an investor recognize whether a stock is generally trending higher or lower. They are not predictions. They are a way to organize information that can otherwise look noisy and random.
What technical analysis does well
Technical analysis can improve trade planning. Rather than buying a stock simply because it seems promising, an investor can decide in advance where to enter, where the idea would be invalidated, and how much capital to risk.
This structure is particularly helpful for shorter-term positions. A strong company can still be a poor short-term purchase if its shares are falling sharply after a major change in expectations. Charts can help investors recognize when market conditions are working against them.
Technical tools can also support risk management for long-term investors. For example, a sharp breakdown on unusually high volume may not mean you must sell immediately, but it may prompt you to review whether new information has weakened the business case.
Where technical analysis falls short
Charts do not reveal a company’s debt burden, product quality, legal risks, or ability to compete. A bullish pattern can fail after an earnings miss, regulatory decision, or economic shock. No indicator can prevent that.
Technical analysis also creates a temptation to overtrade. Investors may fill charts with indicators, interpret every small movement as a signal, and pay unnecessary trading costs. More activity does not equal better decision-making. A simple process used consistently is usually more useful than a complicated chart used emotionally.
Which Method Is Better for You?
Your investing objective should guide the answer. A person contributing regularly to a retirement account and buying diversified funds does not need to become an expert chart reader. Their highest-value decisions may be setting an appropriate asset allocation, keeping costs low, and staying invested through market declines.
An investor selecting individual stocks for a long-term portfolio should put fundamental analysis first. They need to understand what they own, why the business can create value, and what could damage the original thesis. Technical analysis can then provide context for position sizing or timing, but it should not replace business research.
For shorter-term trading, technical analysis may take the lead because price behavior and risk control are central to the strategy. Even then, fundamental awareness matters. Earnings dates, economic reports, and major company announcements can cause large gaps that technical levels alone cannot protect against.
The most practical approach for many intermediate investors is to assign each method a clear job. Use fundamentals to decide whether a company deserves a place on your watchlist or in your portfolio. Use technical analysis to assess whether the market trend supports your planned entry and to establish a level where you will reconsider the position.
A Disciplined Way to Combine Both Approaches
Imagine you find a company with steady revenue growth, manageable debt, healthy free cash flow, and a valuation that appears reasonable compared with similar businesses. That is a fundamental case, not a guarantee. Before buying, you might look at the chart and see that shares have fallen below a major support area after disappointing guidance.
You have choices. You could buy a small initial position because your long-term thesis remains intact. You could wait for the price to stabilize and for volume to show renewed demand. Or you could decide that the weaker outlook changes the fundamental case enough to avoid the stock entirely. The right decision depends on your time horizon, risk tolerance, and evidence, not on a rigid rule.
Keep the analysis separate from the decision. Write down why you are considering the investment, what evidence supports it, how much you are willing to lose, and what would cause you to sell. This prevents a chart pattern from becoming an excuse for owning a weak business or a good story from becoming an excuse for ignoring a deteriorating price trend.
Markets reward patience less consistently than many investors expect, but they do reward preparation. Choose the tools that fit your goal, limit the risk you take on any one decision, and give yourself a process you can still follow when the market becomes uncomfortable.